JAMIEL J
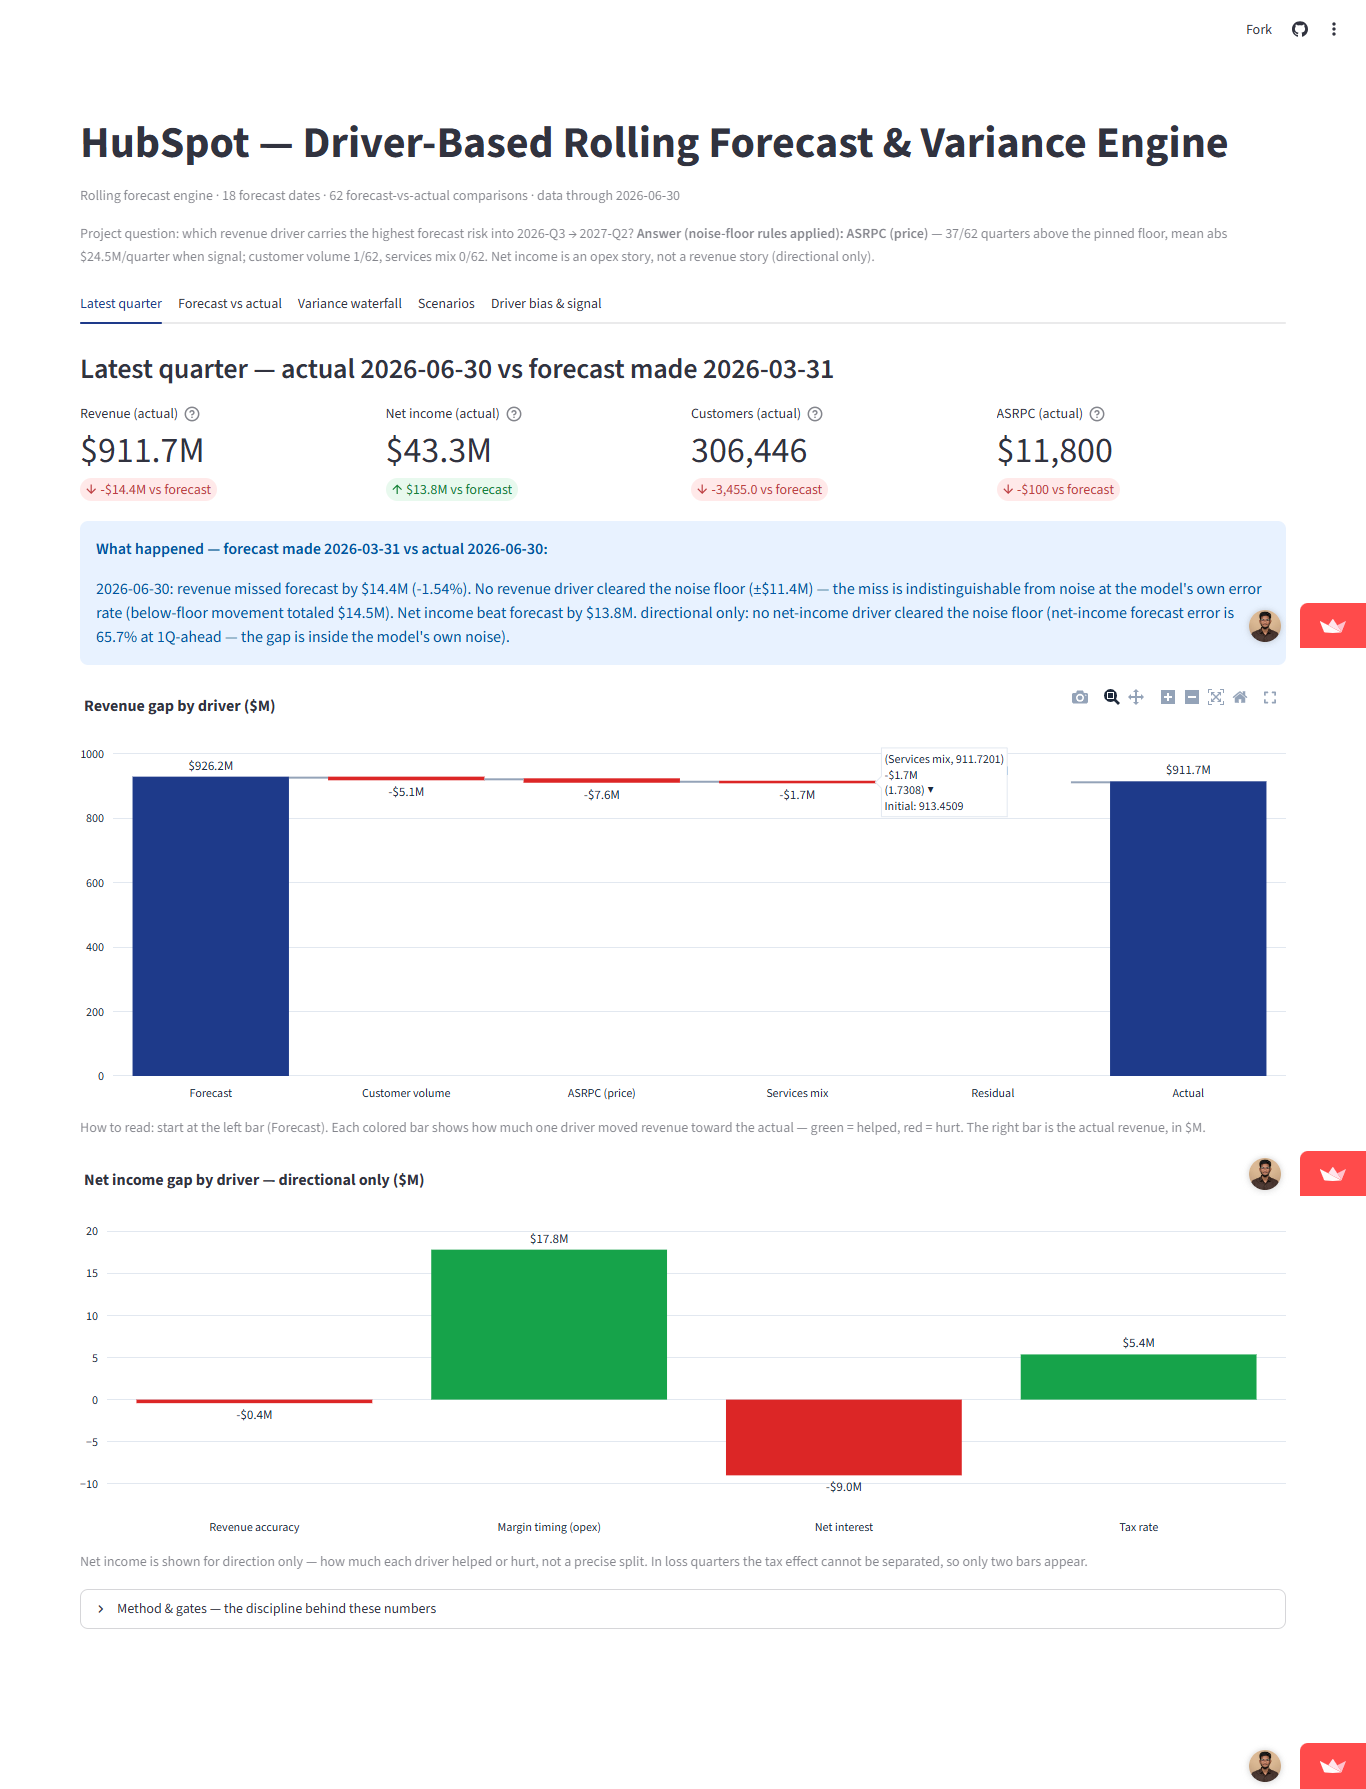
I'm Jamiel — a data analyst from Pudukkottai, Tamil Nadu, focused on financial modeling, FP&A, and everything data. I've built an 18-quarter NII attribution model for JPMorgan Chase, a 30-quarter rolling forecast engine for HubSpot, a Citigroup FY2025 variance model, and credit-risk stress tests on a $7.5B book. B.Tech IT (M.I.E.T) · trained at BY8LABS AI · open to full-time FP&A and analyst roles.
Skills
Data Analysis
- • SQL (PostgreSQL, MySQL)
- • Exploratory Analysis (EDA)
- • Financial Modeling
- • KPI Reporting
Data Engineering
- • DuckDB In-Memory Engines
- • FastAPI Microservices
- • Query Planning (104ms p95)
- • Automated Validation
Machine Learning
- • Scikit-Learn
- • LightGBM / XGBoost
- • Threshold Tuning (SMOTE)
- • Time-Series Forecasting
Visualization
- • Power BI
- • Tableau
- • Streamlit
- • Excel Analytics
Selected Works
All projects →JPMorgan NII Attribution
NII Attribution
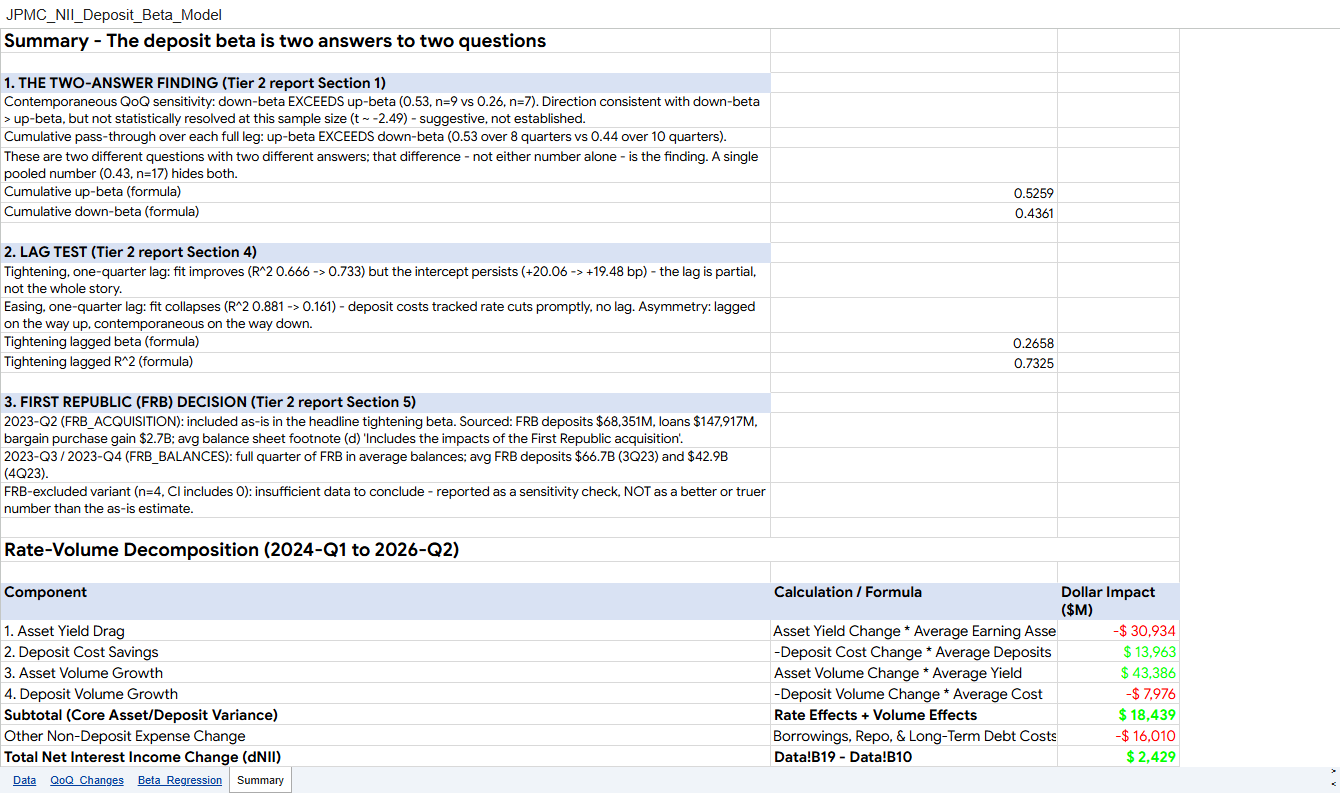
Net interest income and deposit-beta attribution across 18 quarters — source-verified from SEC EDGAR and FRED in a formula-verified workbook.
Citigroup Expense Variance
FP&A Modeling
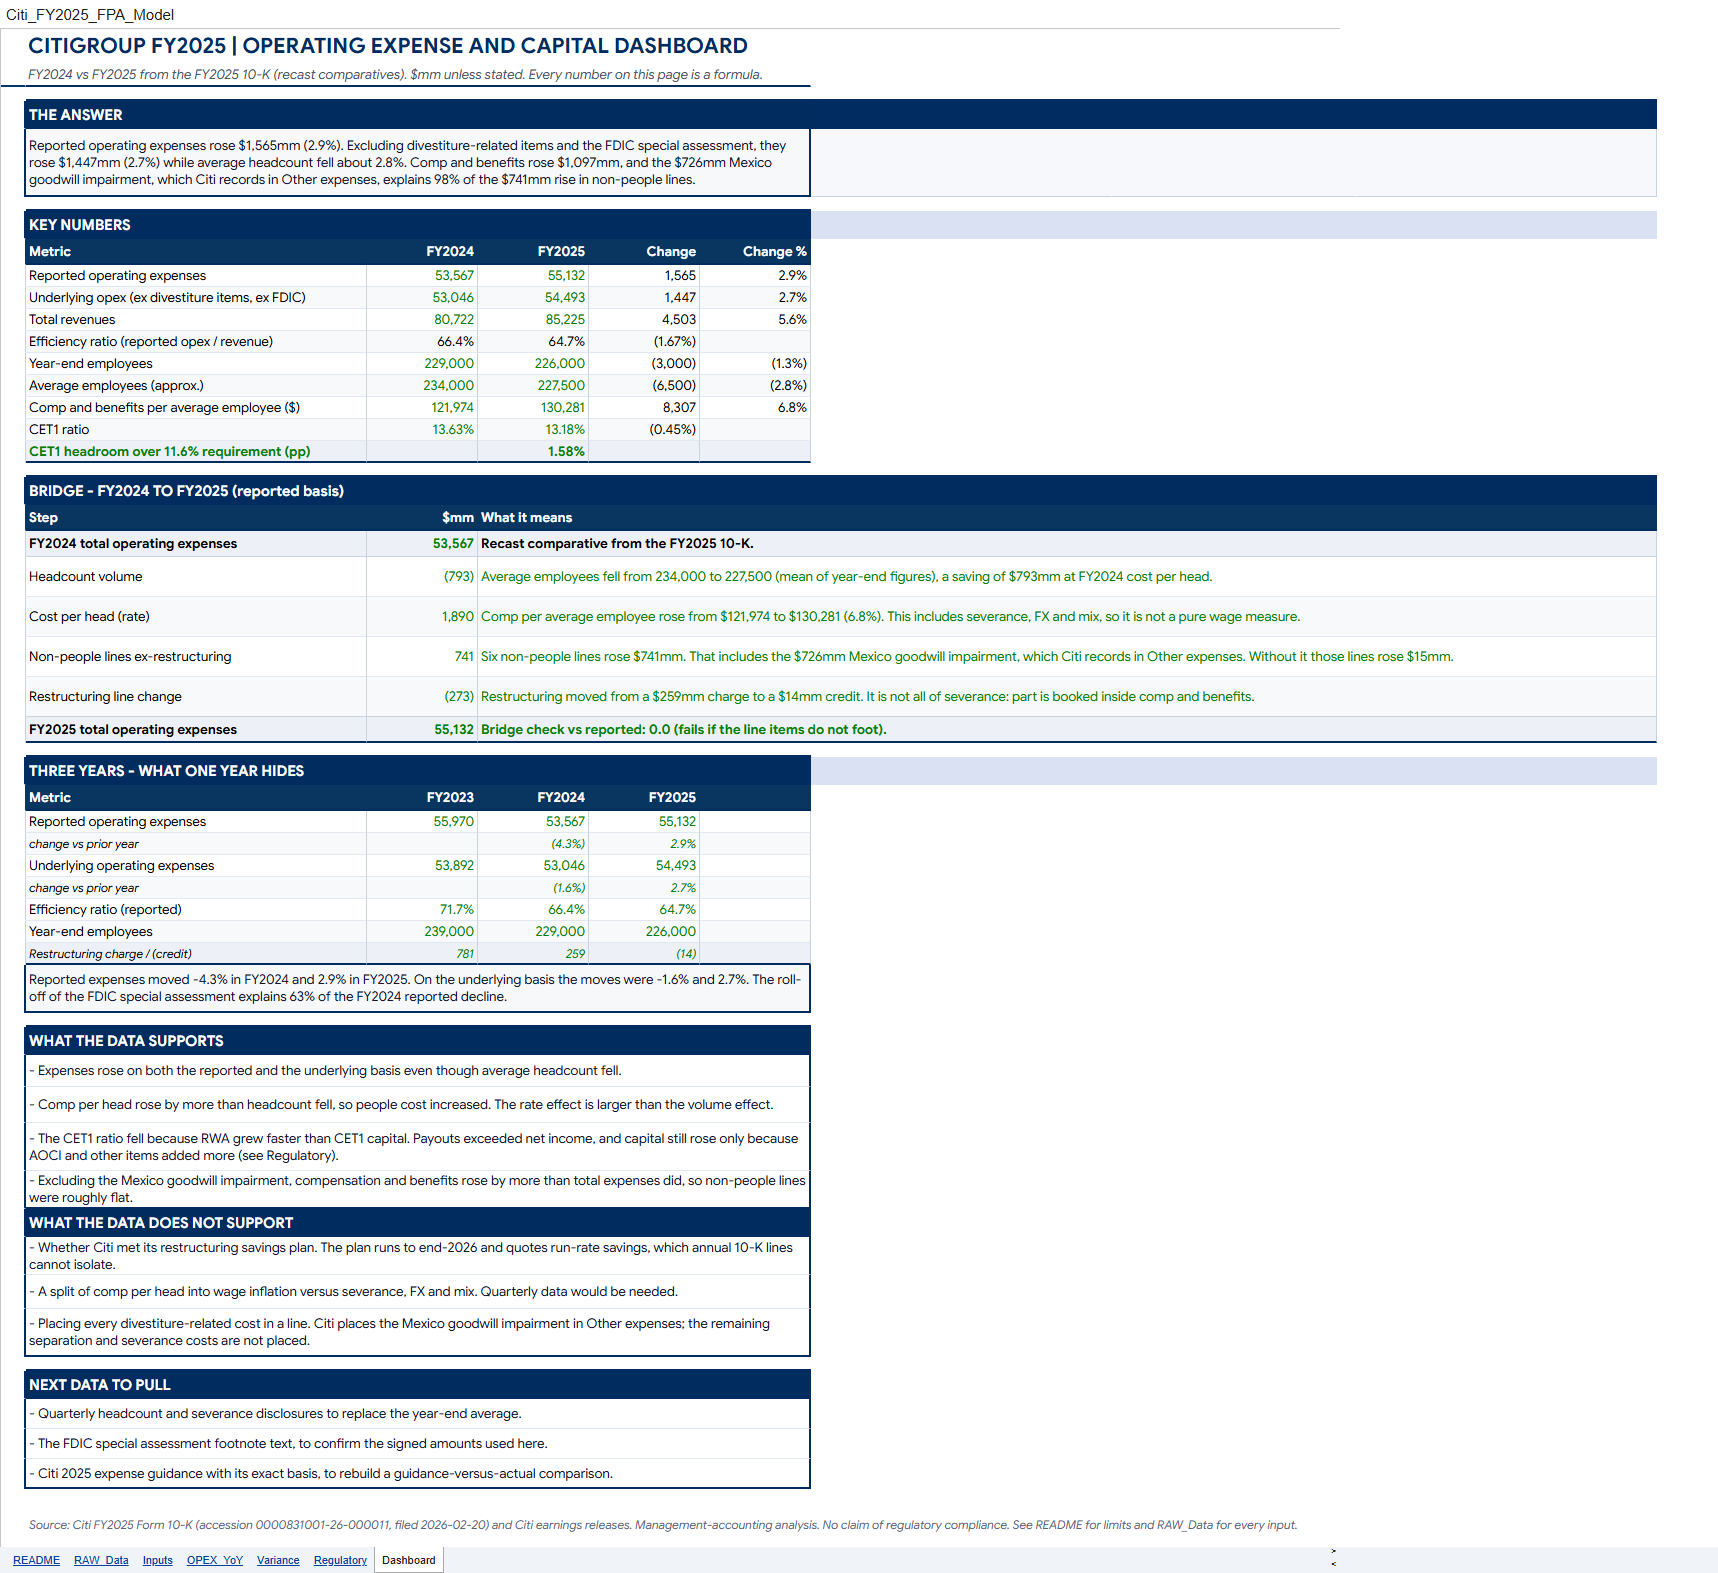
Excel FP&A model explaining why Citigroup's operating expenses rose 2.9% in FY2025 — volume/rate splits, FY24→FY25 bridge, CET1 tied to the 10-K with live integrity checks.
Credit Risk Scoring
ML Risk Modeling
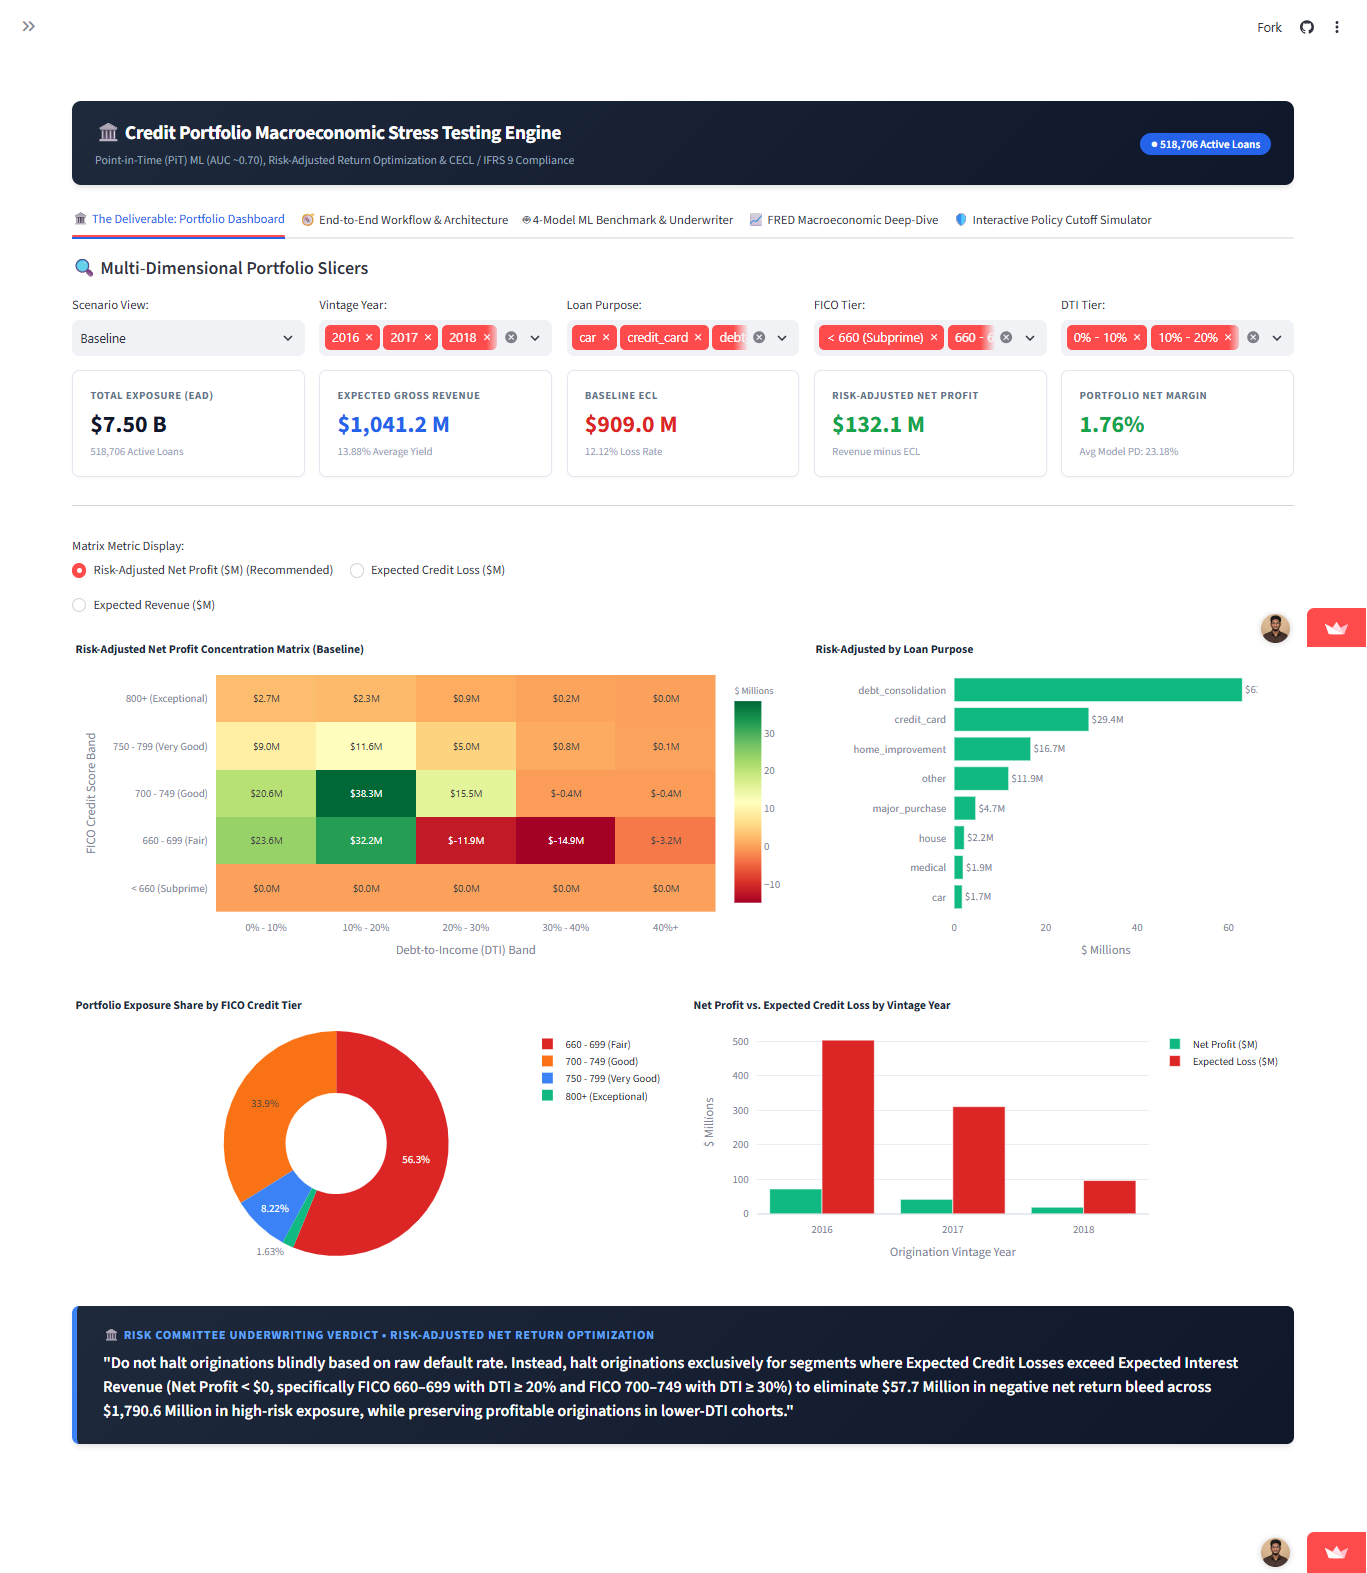
ML-driven credit risk analysis with borrower segmentation and cost-aware recovery strategy.