Credit Risk Scoring
ML-driven credit risk analysis with borrower segmentation and cost-aware recovery strategy.
Challenge
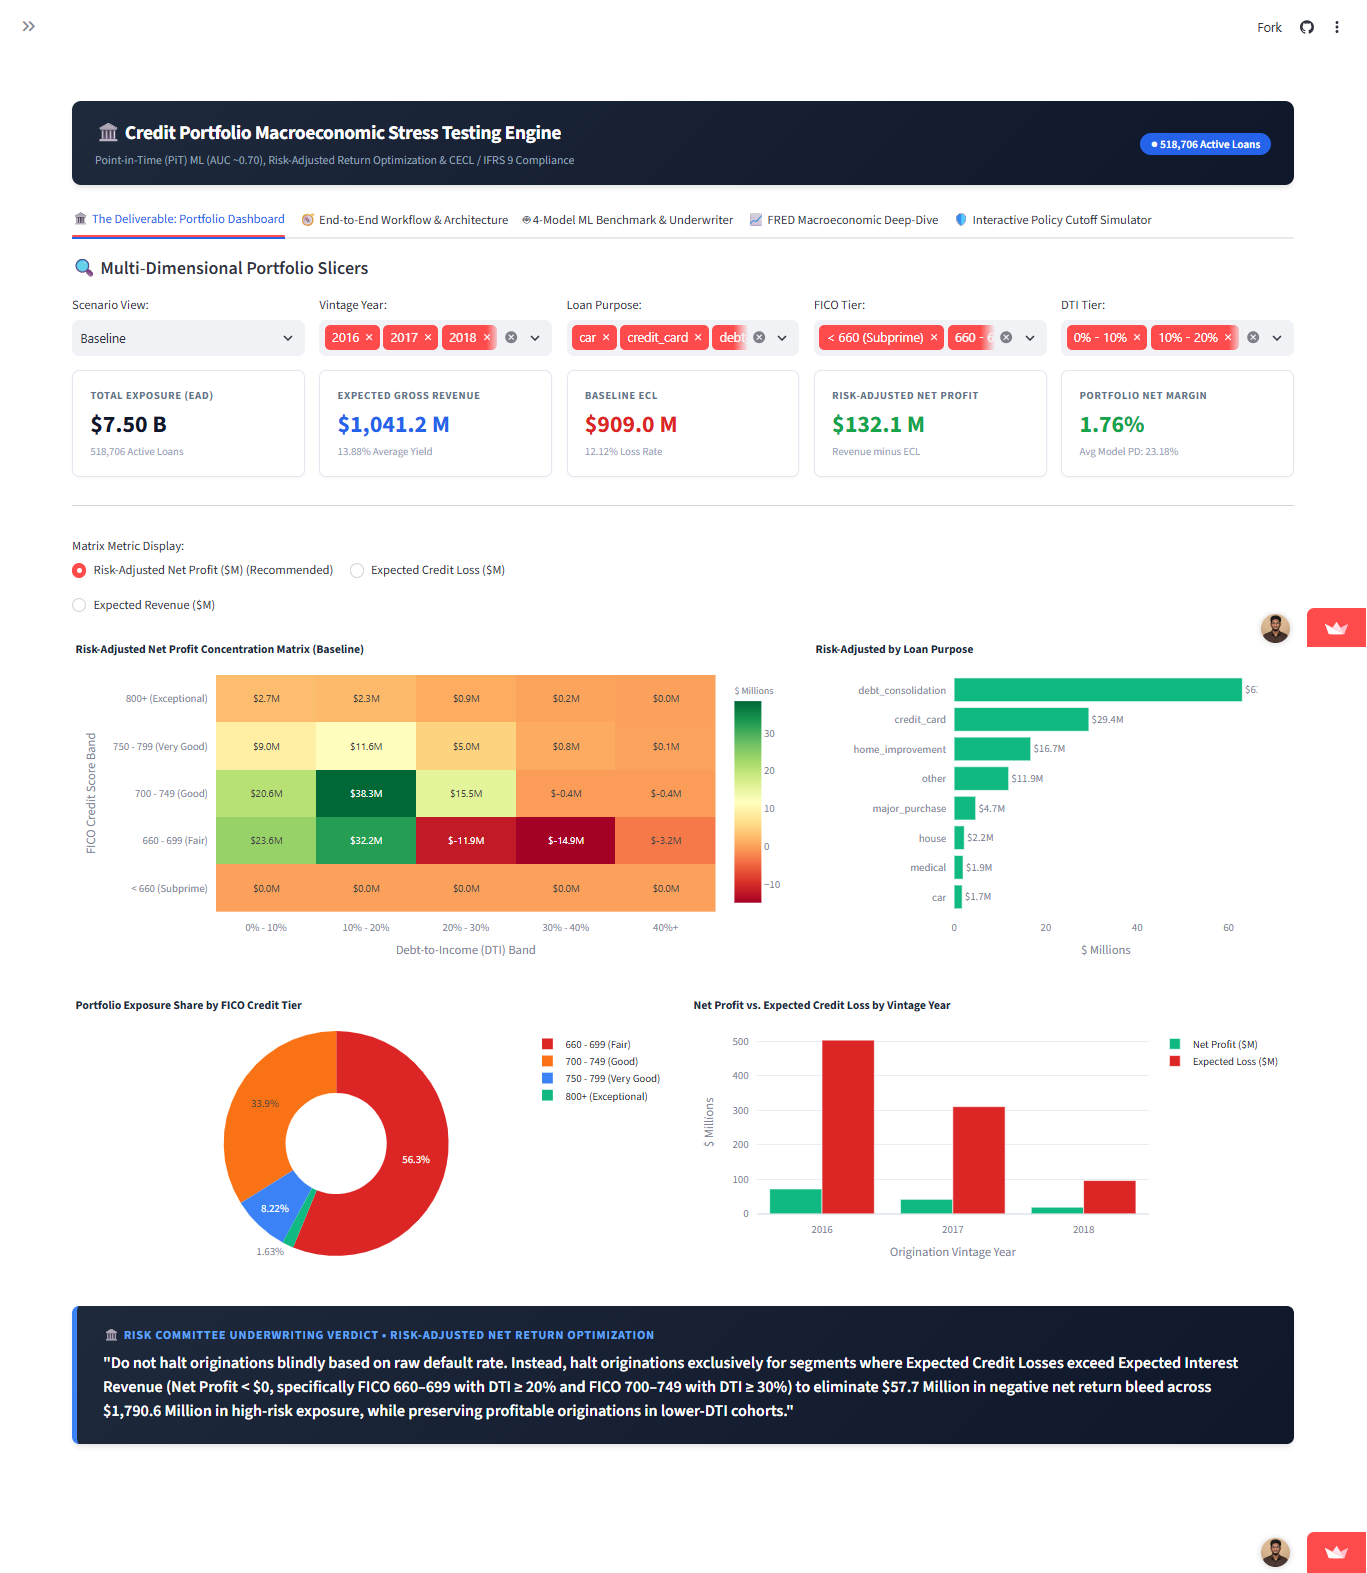
Through-the-cycle scorecards judge borrowers on static attributes while ignoring the macro weather — unemployment and rates that actually drive defaults. Worse, halting originations on high default rates alone is financially suboptimal: borrowers paying 14–18% cover their losses and still print positive net returns.
Solution
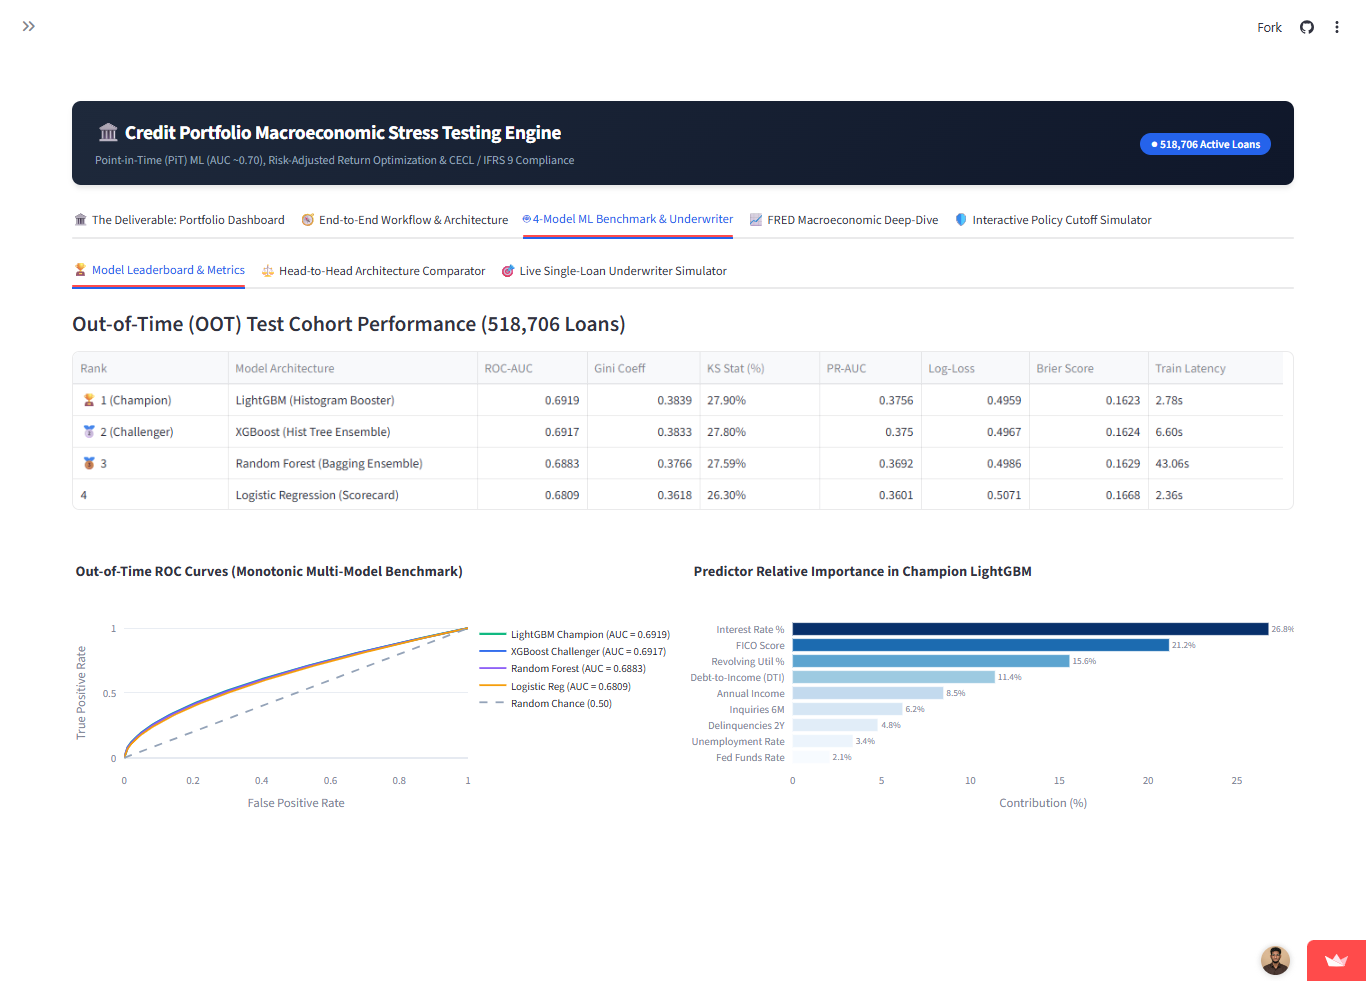
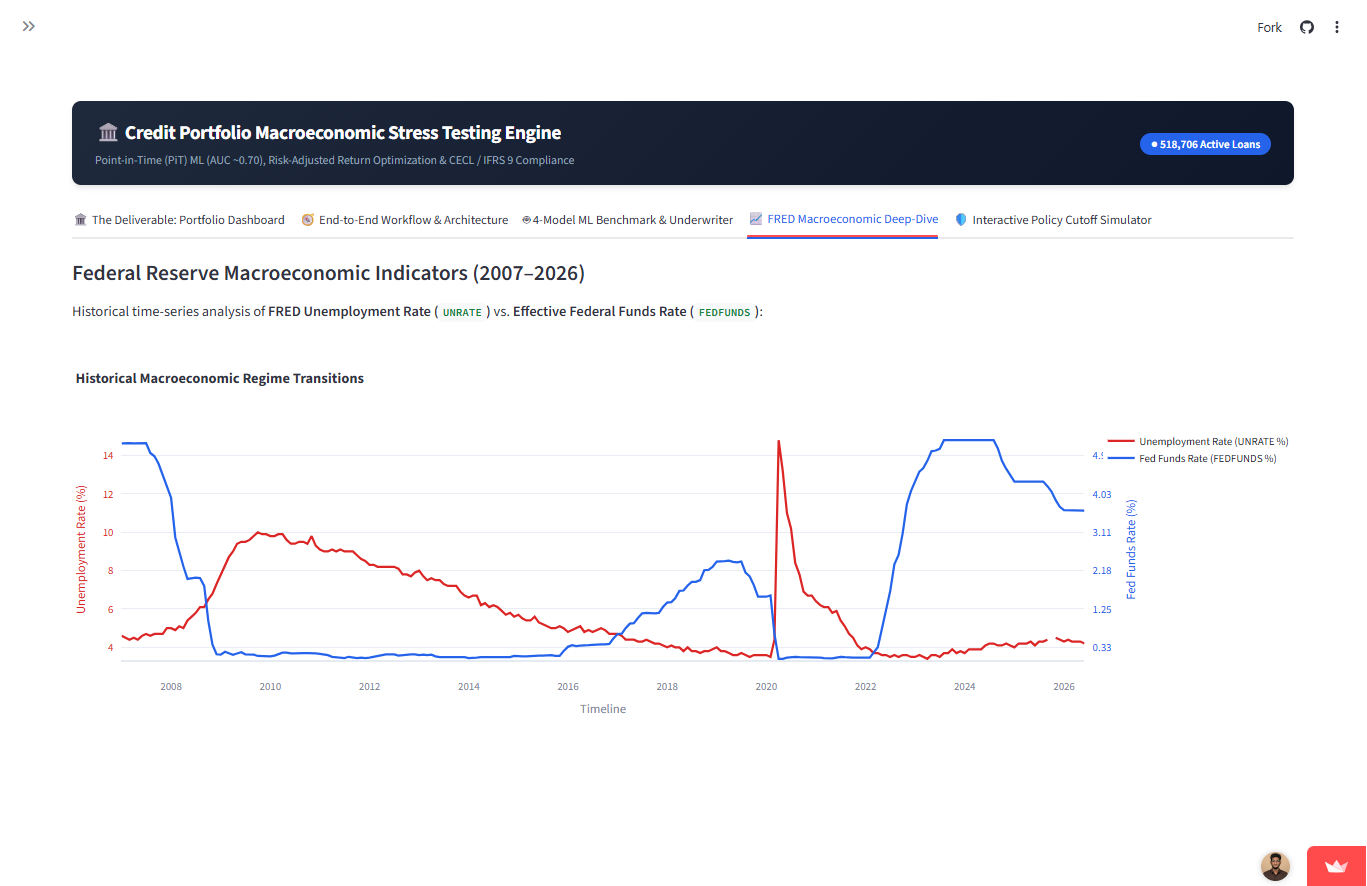
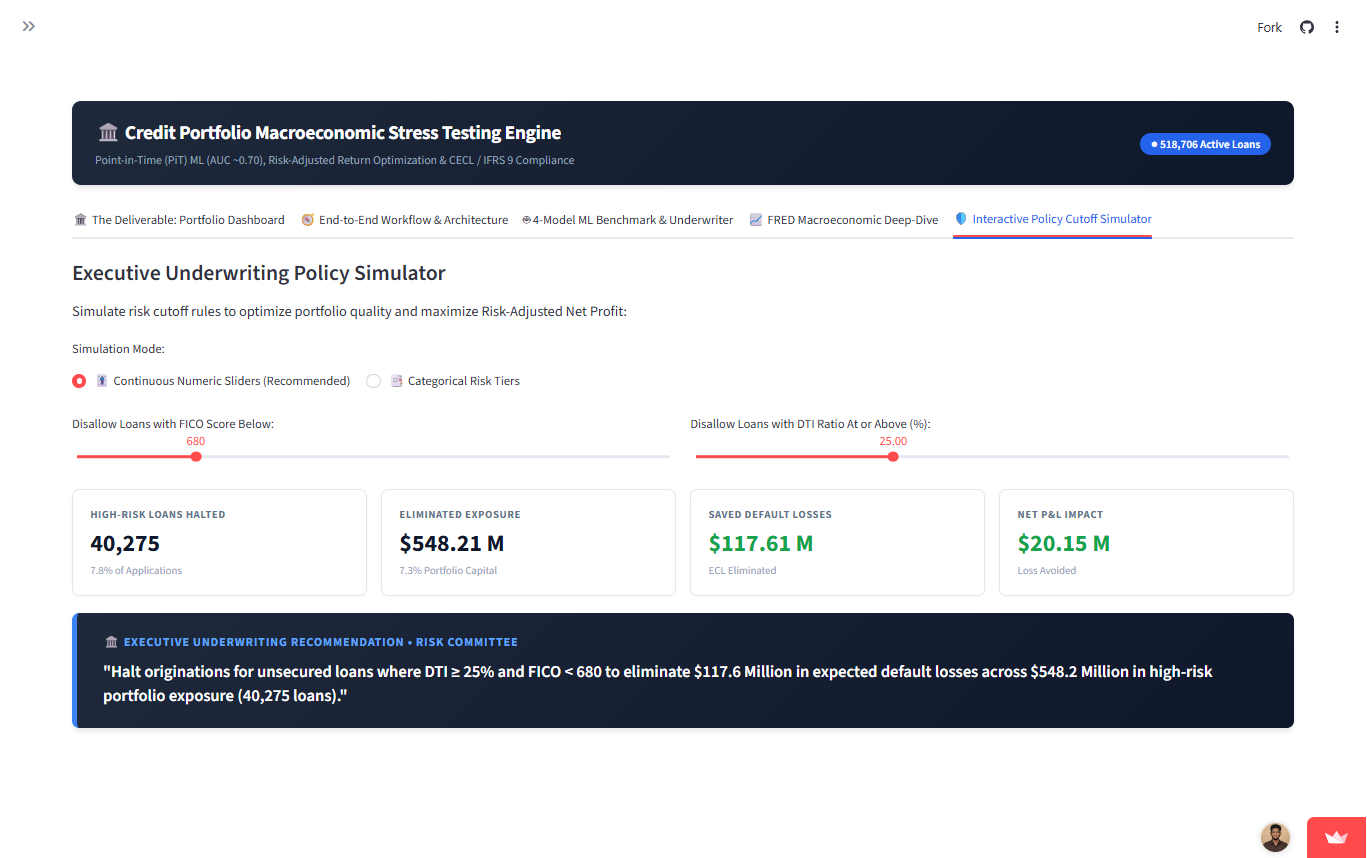
Built a 5-phase engine on 1.34M LendingClub loans plus 234 months of FRED macro data in DuckDB: a LightGBM champion (0.6919 out-of-time ROC-AUC) for point-in-time default risk, econometric shocks (+3.5% UNRATE, +1.5% FEDFUNDS) quantifying a $32.8M severe ECL expansion on the $7.5B book, and a SQL net-profit matrix (ECL = PD × 0.50 × EAD) that halts only loss-making FICO/DTI cells — killing $30.8M in net losses while preserving $55.7M of profitable originations, served through a 5-tab Streamlit app with Power BI exports.
View GitHub Repo